
 Solvency Requirements

At the end of the year, new regulations that are important for the financial sector will take effect. The A few years ago, the European Commission launched the Green Deal, aimed at achieving the 2050 climate goals. One of the pillars of the Green Deal focuses on the financial sector, which must play an active role in the energy transition. Financial institutions are not only required to align their own operations with climate goals but also to factor the impact of their lending and investments into their decision-making.
“After the 2008 financial crisis, the financial sector was already under close scrutiny,” says Korthals Altes. “Solvency requirements were initially around 3 percent and were subsequently raised to a minimum of 13.5 percent. As a result of the Green Deal, an additional category is now being introduced: green loans. If banks lend money for projects that meet certain environmental requirements, they are required to hold less capital for those loans. That means those loans will yield higher returns. So a new market is being created. A company that wants to invest will receive a lower interest rate if it meets the conditions. On the demand side, something new is also being created: if you build a cold storage facility and install solar panels on it, you can finance the entire facility at a lower interest rate. That can be very attractive.”
Of course, that won’t happen overnight. Banks will face extensive reporting requirements and will have to impose new requirements on their customers. Whereas they used to be able to limit themselves to the financial implications of a loan, they will now have to collect all kinds of data about their customers. And more importantly, they will have to provide advice that goes beyond traditional financial frameworks. “So far, banks have generally continued to use the same forms, with just a few extra fields,” says Korthals Altes. “But that’s bound to change. We’ll start to see increasingly sophisticated corporate financing arrangements, where, for example, it’s agreed that if you achieve a certain reduction in energy or water consumption in two or three years, the interest rate will go down—or won’t go up.” Under competitive pressure, banks will have to innovate and adapt more quickly.

Other Skills and Roles
 Other Skills and Roles
The implementation of the new products and the reporting requirements call for a different approach from financial institutions. “Banks will have to develop entirely different skills; they will almost have to become organizational consultants for their clients. They will also need to acquire new expertise on topics such as energy conservation, alternative energy sources, and the payback period for new investments. Some banks have been working on this for a while. Triodos derives its raison d’être from this. BNP Paribas has partnered with an engineering firm to determine which data are important, and the—large but relatively unknown—Dutch Water Board Bank is also working on it. “As a bank, you can try to do everything yourself, but sometimes it’s smarter to build an ecosystem to tap into knowledge and expertise.”
Banks will have to start collecting different types of data over the term of a loan. “Until now, they have focused exclusively on financial data, but they must now also collect data on energy consumption and CO2 emissions. Will the agreed-upon reduction actually be achieved? Banks are still grappling with how to measure and record this.” What data is involved? How reliable is it? They must also be able to demonstrate the quality of the ESG data to shareholders. If the data is inaccurate, an investor may start asking questions at some point. And before you know it, legal liability comes into play.”
Dilemmas
 Dilemmas
The new situation presents various dilemmas. Just consider the time frame we’re talking about. The average term of a business loan is six years, so banks are used to thinking in relatively short cycles. “All kinds of calculations have been made regarding the energy transition. The money is there—that’s not the problem. But when a banker looks at the probability of default, he’s assessing whether a company can repay its loan within six years. Unforeseen circumstances can arise: energy costs may rise, or there may be flooding. But over a six-year period, those problems are manageable. Over a period of 25 or 30 years, however, those factors play a much greater role. If a bank wants to finance a farmer, one dry summer in five years isn’t a disaster. But will that farmer still be active in agriculture 25 years from now? That time horizon is certainly a complicating factor.”
How can we resolve this dilemma? Pension funds do have a long-term perspective and can therefore offer a solution. “Some pension funds have entered the mortgage market,” Korthals Altes explains by way of example. “They don’t do this themselves, but have set up a fund for that purpose. Mortgage lending is typically an activity that a bank can handle. The funding doesn’t have to come from the bank itself. The pension fund has the money, the bank has the expertise and the customers. In short, new structures can be devised. This form of collaboration could be an interesting niche for a bank. A great example of product innovation.”
Another dilemma concerns the type of clients. If banks are required to have a certain percentage of green investments on their balance sheets, they may consider divesting certain clients. Korthals Altes cites shipping companies as an example. “Ships aren’t exactly environmentally friendly, given the fuel oil they consume. There’s little indication that this will change in the next five years. Yet the shipping industry will still need to be financed. A shipowner can, of course, turn to a European bank, but he can also choose an Arab country that’s happy to continue financing this industry. The bank can make that choice for itself as well. You can become greener by issuing more green loans, or you can become greener by issuing fewer gray loans. But then you’ll have to part ways with some clients. That’s a strategic choice: if you stop providing ship financing, your balance sheet will become greener. Or the bank might say: “I’m going to actively engage with shipowners to see what we can finance. Could we make shipping greener using alternative means?” In that case, the bank takes on a role in providing innovation advice to its clients. Until recently, that was unthinkable.”


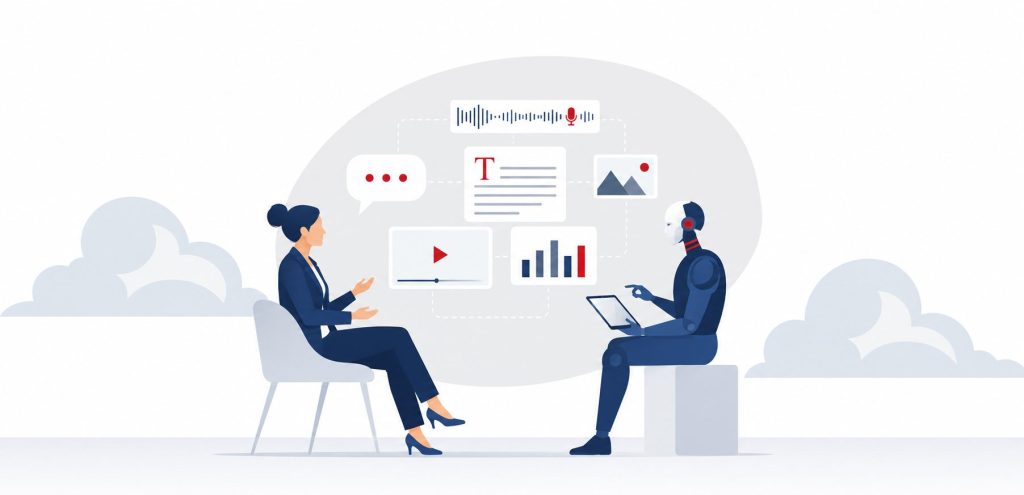

A form has never been the best way to understand someone. AI enables multimodal input.
From minimal input to rich context: AI-driven multimodal input is transforming how financial institutions make decisions.

Banks, Start Using AI Now to Help Entrepreneurs
Artificial Intelligence Banks, Start Using AI Now to Help Entrepreneurs Since the start of the COVID-19 crisis, the government has been trying to keep businesses

Aegon
Business Property Damage Transition Aegon Netherlands Clear Vision Driven by core values New criteria as the deciding factor From Vision to Execution Insurer Aegon has

BNR | Why not try starting a platform?
Platformization Why not try starting a platform? BNR The Technologist Turner’s Antal Ruiter was a guest on BNR’s “De Technoloog” for an hour on Thursday,

Have the major platforms become too big?
Platformization Have the major platforms become too big? The growth of online platforms continues, despite—or perhaps because of—the COVID-19 crisis. Major players, in particular, are

Ten Recommendations for Implementing Your Platform Strategy
Platformization Ten Recommendations for Implementing Your Platform Strategy Online platforms are all the rage. From retail platforms to social media, and from lodging to taxi

Big Data and AI: Where Do You Stand?
Big Data and AI: Where Do You Stand? Turner data scientist Egbert Clevers reflects in the car on the ubiquity of big data and AI. Everyone uses AI. But how

Taking AI Beyond the Experimental Stage?
Artificial Intelligence Taking AI Beyond the Experimental Stage? It Starts with Focus. Frits Korthals Altes of Turner writes about Artificial Intelligence (AI) in his latest

5 Data Governance Tips
Artificial Intelligence 5 Data Governance Tips: Don’t Let Your “Data Lake” Turn Into a “Data Swamp” Frits Korthals Altes of Turner sees many organizations starting

Recommendations for the Implementation of New Payment Standards
“The Right Healthcare in the Right Place”—it’s easier said than done. The patient’s journey often involves navigating many barriers. Yet we know that to provide optimal healthcare, we must break

Six Archetypes of Data Scientists—CHOOSE Your Color
Artificial Intelligence Six Archetypes of Data Scientists—CHOOSE Your Color Data scientist Egbert Clevers has to explain “what he actually does” all over again at every

Why Platformization Should Be a Top Priority Right Now
We don’t know exactly what the financial world will look like after the COVID-19 crisis. So far, the impact on banks and insurers appears to be limited. But the pandemic